
06.08.2026
News
Monthly Recap: July 2026

As we enter the third quarter, we take a moment to review the performance of our strategies in July.
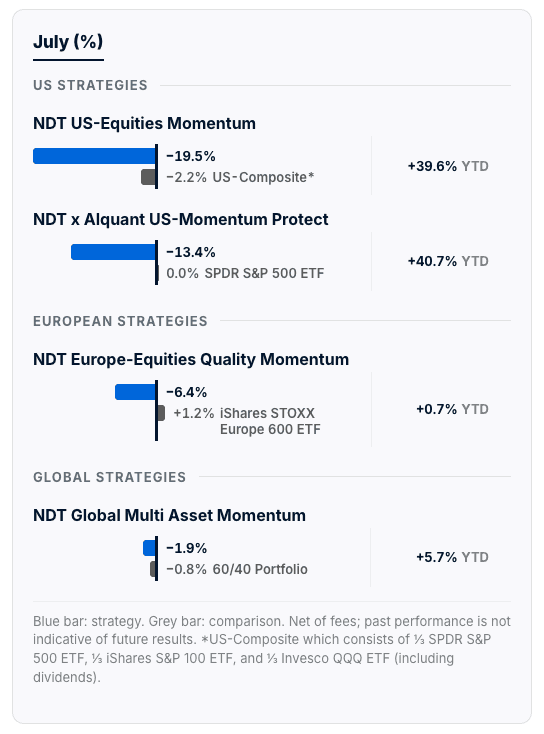
After an extended period of strong gains the past months, July was marked by a sharp pullback in the technology sector. Given the positioning of our strategies, performance came under pressure over the month.
Performance Update (as of the close of July 31, 2026)
Market Commentary
US equities & economic backdrop: US equities were volatile in July, with the Nasdaq 100 falling 6.6%. Market leadership shifted toward value, energy and financial stocks, while technology lagged. The Fed held rates at 3.50%–3.75% as inflation eased to 3.5% in June. Strong Q2 earnings growth of more than 20% helped offset macroeconomic uncertainty.
Key drivers: Asia’s AI trade reversed sharply in July following strong Q2 gains. The KOSPI fell almost 40% from its June peak, its worst monthly decline on record, as fading chip enthusiasm and leveraged ETFs amplified the selloff.
Eurozone & global: Developed markets outside the US held up better, with MSCI Europe ex-UK up ~1.5% and UK equities up ~2% on energy exposure. Japan's TOPIX fell as the chip selloff spread (Nikkei -8%). China bucked the trend, with Hong Kong and MSCI China up ~10%, while MSCI EM slipped ~2%.
Rates, sectors & themes: Treasury yields hit 2026 highs on the inflation scare and hawkish Fed, the 10-year up ~20bps to 4.70% and the 2-year at 4.25%. Long bonds fell hardest (20yr+ Treasuries -3.9%, US Agg -1.4%), while high yield held up (-0.5%). Energy led S&P 500 sectors and financials rose, while tech and utilities lagged and value beat growth.
Commodities & other assets: Commodities led all asset classes on energy strength, with Brent and WTI both up ~17%, copper +7% and wheat +11%. Precious metals fell as real yields rose, unwinding some of the year's safe-haven bid. Natural gas slumped 15%, while Bitcoin was flat on the month but down ~28% YTD.
Our Worst Detractors in the US
In July, NDT US-Equities Momentum came under pressure as momentum, growth and AI-related stocks corrected sharply. The sell-off was concentrated across the AI infrastructure value chain, while less cyclical holdings including Eli Lilly, GE Vernova and Caterpillar, proved more resilient and partially offset the decline.
The drawdown primarily reflected a rotation away from recent market leaders rather than a broad market downturn or a deterioration in company fundamentals. The portfolio maintained 75% market exposure during the month, with 25% allocated to cash, reflecting the model’s more measured positioning amid elevated volatility.
At the beginning of July, we also launched the NDT x Alquant US-Momentum Protect strategy for clients seeking a lower-volatility version of our US-Momentum strategy. Its risk overlay performed as intended, reducing the monthly decline by 6.1 percentage points while preserving participation in potential upside.

Putting the recent pullback into perspective
Since 2000, the strategy has experienced seven distinct drawdowns of more than 20%. Over the subsequent 12 months, it outperformed the Nasdaq-100 in six of the seven cases. Across all seven observations, the strategy’s median 12-month return was approximately 24%.
Past performance is not indicative of future results and the current drawdown may develop differently. Nevertheless, these observations provide useful historical context for investors assessing the strategy after the recent decline.
Our Top Performers in Europe of April 2026
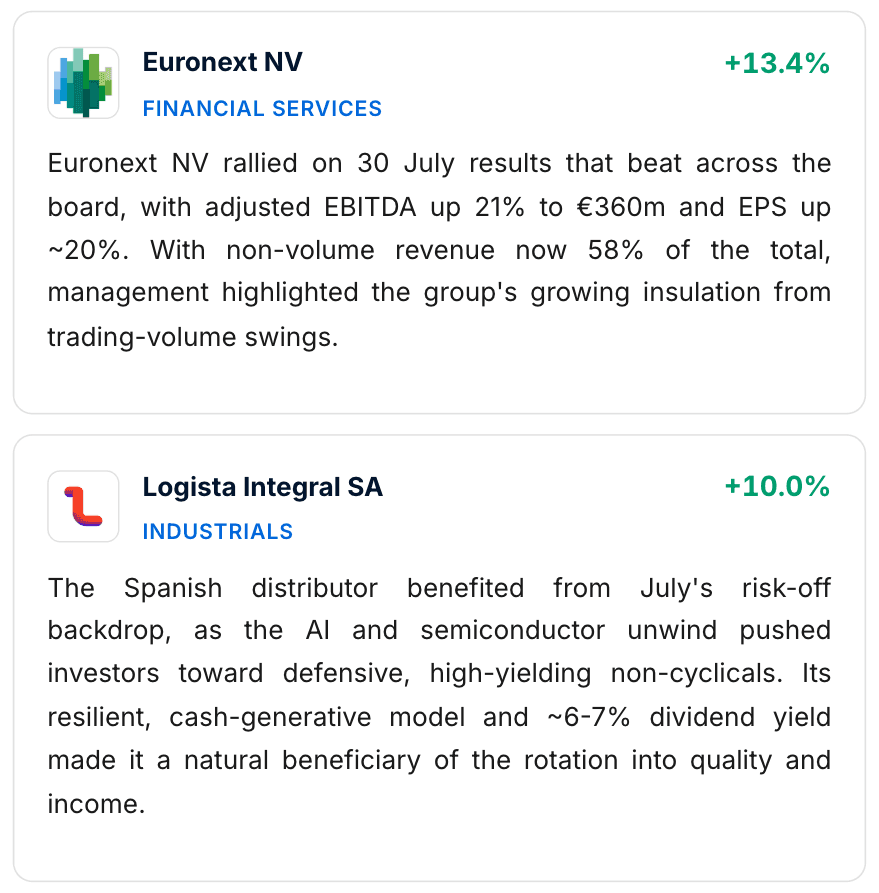
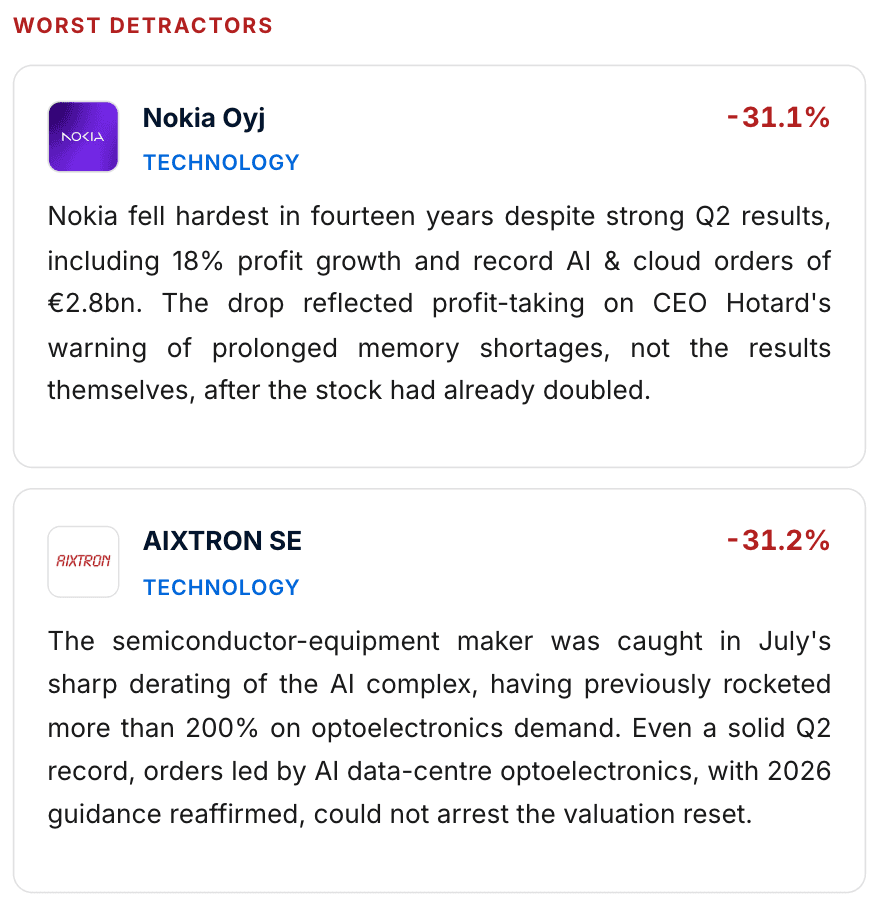
In July, our European strategy came under pressure as the correction in AI- and semiconductor-related stocks spread to Europe, intensified by weaker guidance from STMicroelectronics. AIXTRON and Nokia were the main detractors, while Euronext and Logista partially offset the decline.
NDT US-Equities Momentum:
A satellite solution to complement existing portfolios with a concentrated selection of US large-cap stocks with strong momentum.
NDT x Alquant US-Momentum Protect:
Our US-Equities Momentum strategy paired with a systematic protection overlay from Alquant, designed to soften drawdowns while keeping momentum upside.
NDT Europe-Equities Quality Momentum:
Complement your portfolio with a selection of high-momentum, quality stocks out of the STOXX Europe 600.
NDT Global Multi Asset Momentum:
A systematic strategy designed to complement discretionary portfolios for long-term participation in global growth.
The strategies had their rebalancing in early August, following July’s market rotation and now reflect the latest signals generated by our models. As always, we remain focused on disciplined and consistent execution, allowing the investment process rather than short-term emotions to guide our decisions.
If you want to chat about the markets or our strategies, please let us know and we would be happy to arrange a meeting.
Thank you for your continued trust and enjoy the rest of the summer.
Best regards,
Team NDT
For marketing purposes only. Advertising according to Art. 68 FinSA. All rights reserved.
Photo by Jakub Pabis
As we enter the third quarter, we take a moment to review the performance of our strategies in July.
After an extended period of strong gains the past months, July was marked by a sharp pullback in the technology sector. Given the positioning of our strategies, performance came under pressure over the month.
Performance Update (as of the close of July 31, 2026)
Market Commentary
US equities & economic backdrop: US equities were volatile in July, with the Nasdaq 100 falling 6.6%. Market leadership shifted toward value, energy and financial stocks, while technology lagged. The Fed held rates at 3.50%–3.75% as inflation eased to 3.5% in June. Strong Q2 earnings growth of more than 20% helped offset macroeconomic uncertainty.
Key drivers: Asia’s AI trade reversed sharply in July following strong Q2 gains. The KOSPI fell almost 40% from its June peak, its worst monthly decline on record, as fading chip enthusiasm and leveraged ETFs amplified the selloff.
Eurozone & global: Developed markets outside the US held up better, with MSCI Europe ex-UK up ~1.5% and UK equities up ~2% on energy exposure. Japan's TOPIX fell as the chip selloff spread (Nikkei -8%). China bucked the trend, with Hong Kong and MSCI China up ~10%, while MSCI EM slipped ~2%.
Rates, sectors & themes: Treasury yields hit 2026 highs on the inflation scare and hawkish Fed, the 10-year up ~20bps to 4.70% and the 2-year at 4.25%. Long bonds fell hardest (20yr+ Treasuries -3.9%, US Agg -1.4%), while high yield held up (-0.5%). Energy led S&P 500 sectors and financials rose, while tech and utilities lagged and value beat growth.
Commodities & other assets: Commodities led all asset classes on energy strength, with Brent and WTI both up ~17%, copper +7% and wheat +11%. Precious metals fell as real yields rose, unwinding some of the year's safe-haven bid. Natural gas slumped 15%, while Bitcoin was flat on the month but down ~28% YTD.
Our Worst Detractors in the US
In July, NDT US-Equities Momentum came under pressure as momentum, growth and AI-related stocks corrected sharply. The sell-off was concentrated across the AI infrastructure value chain, while less cyclical holdings including Eli Lilly, GE Vernova and Caterpillar, proved more resilient and partially offset the decline.
The drawdown primarily reflected a rotation away from recent market leaders rather than a broad market downturn or a deterioration in company fundamentals. The portfolio maintained 75% market exposure during the month, with 25% allocated to cash, reflecting the model’s more measured positioning amid elevated volatility.
At the beginning of July, we also launched the NDT x Alquant US-Momentum Protect strategy for clients seeking a lower-volatility version of our US-Momentum strategy. Its risk overlay performed as intended, reducing the monthly decline by 6.1 percentage points while preserving participation in potential upside.
Putting the recent pullback into perspective
Since 2000, the strategy has experienced seven distinct drawdowns of more than 20%. Over the subsequent 12 months, it outperformed the Nasdaq-100 in six of the seven cases. Across all seven observations, the strategy’s median 12-month return was approximately 24%.
Past performance is not indicative of future results and the current drawdown may develop differently. Nevertheless, these observations provide useful historical context for investors assessing the strategy after the recent decline.
Our Top Performers in Europe of April 2026
In July, our European strategy came under pressure as the correction in AI- and semiconductor-related stocks spread to Europe, intensified by weaker guidance from STMicroelectronics. AIXTRON and Nokia were the main detractors, while Euronext and Logista partially offset the decline.
NDT US-Equities Momentum:
A satellite solution to complement existing portfolios with a concentrated selection of US large-cap stocks with strong momentum.
NDT x Alquant US-Momentum Protect:
Our US-Equities Momentum strategy paired with a systematic protection overlay from Alquant, designed to soften drawdowns while keeping momentum upside.
NDT Europe-Equities Quality Momentum:
Complement your portfolio with a selection of high-momentum, quality stocks out of the STOXX Europe 600.
NDT Global Multi Asset Momentum:
A systematic strategy designed to complement discretionary portfolios for long-term participation in global growth.
The strategies had their rebalancing in early August, following July’s market rotation and now reflect the latest signals generated by our models. As always, we remain focused on disciplined and consistent execution, allowing the investment process rather than short-term emotions to guide our decisions.
If you want to chat about the markets or our strategies, please let us know and we would be happy to arrange a meeting.
Thank you for your continued trust and enjoy the rest of the summer.
Best regards,
Team NDT
For marketing purposes only. Advertising according to Art. 68 FinSA. All rights reserved.
Photo by Jakub Pabis